Buying your first home in Southern California?
Know your number before you shop.

See how much cash you really need to buy in Rancho Cucamonga, Fontana, Rialto, Highland, Redlands or San Bernardino, which loan fits you, and which California down payment programs are worth asking about.

Figure out my cash to close See assistance programs
$549KSan Bernardino County median sale price (3 months to Sep 2026)
$690,0002026 FHA loan limit, San Bernardino County
$832,7502026 conforming limit before jumbo
~$3,000/moMedian rent in Rancho Cucamonga and Fontana
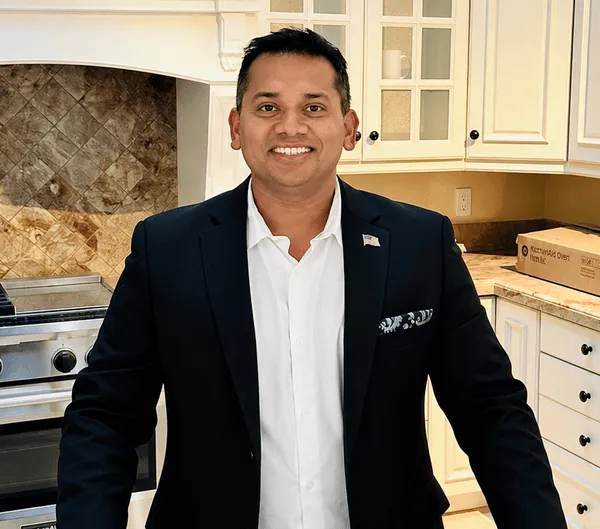
Sunny Randhir Singh, REALTOR, eXp Realty

A first home, then a second

"He helped me buy my first home back in 2022, and from that very first step, I knew I was in the best hands... When it came time to sell my home, Sunny went above and beyond yet again. My home was only on the market for 5 days before we entered escrow."
Sunny's client, first-time buyer in 2022

How much cash do you need to buy?

Your down payment is only part of it. This adds up what a buyer typically pays in San Bernardino County, from the appraisal to your first year of insurance, so there are no surprises at closing.

Base rate is 1% plus local bonds, usually about 1.1% to 1.25%.
Common in newer tracts (north Fontana, parts of Rancho). Ask for the exact figure on any listing.
Total cash you'll need
$0

Before closing

At closing

Estimated monthly payment: $0

Your deposit (earnest money, usually 1% to 3%) goes into escrow and is credited toward your down payment, so it's counted once here.

Want this breakdown sent to you?

We'll send your numbers and the programs worth asking a lender about, and Sunny will reach out personally.

Renting vs. buying in Rancho Cucamonga and nearby

Median rent in Rancho Cucamonga and Fontana is about $3,000 a month (Realtor.com, fall 2026). Here's how that compares with owning at the price you picked above.

Rent:
Own:

Owning also builds equity with every payment, and California's Prop 13 caps how much your assessed value can rise each year (2% max).

Which loan fits you?

The loan you pick changes your down payment, your mortgage insurance and your cash to close. Your lender confirms what you qualify for.

Conventional

As little as 3% down for first-time buyers. Mortgage insurance (PMI) until you reach 20% equity, then it can come off.

FHA

3.5% down with more flexible credit. Upfront and monthly mortgage insurance. 2026 limit in San Bernardino and Riverside counties: $690,000 for a single-family home.

VA

0% down and no monthly mortgage insurance for veterans and service members. A one-time funding fee, waived if you receive VA disability compensation.

CalHFA

State-backed first mortgages (FHA or conventional) for low- to moderate-income first-time buyers, which can be paired with CalHFA down payment help below.

Jumbo

For loans above the 2026 conforming limit of $832,750, common in north Rancho Cucamonga and Alta Loma. Usually needs more down and stronger credit.

New construction

Builders in Fontana, Rialto and Highland sometimes offer closing-cost credits or rate buydowns, especially with their preferred lender. Bring your own agent from the first visit, it costs you nothing.

Down payment help in California and San Bernardino County

Most first-time buyers have never heard of these. This is a list of programs worth asking about, not an approval. Rules, income limits and funding change often, and only an approved lender can tell you if you qualify. Checked October 2026.

Open

CalHFA MyHome Assistance

Up to 3.5% of the price (FHA) for down payment or closing costs. A deferred loan: no monthly payment, repaid when you sell, refinance or pay off the home. First-time buyers, income limits apply. Used with a CalHFA first mortgage.

Official page
Open

CalHFA Zero Interest Program (ZIP)

A 0% deferred loan of 2% or 3% of the loan amount for closing costs. Used with CalHFA's CalPLUS Conventional loan. First-time buyers only.

Program list
Rounds

California Dream For All

Up to 20% of the price (max $150,000) for first-generation buyers. You repay the amount plus a share of the home's appreciation when you sell. Funding comes in lottery rounds: vouchers for the latest round went out May 2026.

Official page
Open

GSFA Platinum

Up to 5.5% of the loan for down payment and closing costs. No first-time buyer requirement, and income limits are often higher than people expect.

Official page
Paused

San Bernardino & Riverside County Down Payment Assistance (NPHS)

Up to $40,000 as a 0% deferred loan for first-time buyers at or below 80% of area median income in San Bernardino or Riverside County. Current funding is fully committed. Watch for the next round.

Program details
Check funding

San Bernardino County and city programs

The county no longer runs its own down payment fund and refers buyers to partner agencies. City programs (like Ontario's Keys to Community) come and go, so ask before you write an offer.

County resource list

Program details summarized from official sources in October 2026 and subject to change. Questions? Call Sunny: 909-233-0756

Your path to the keys

Talk to Sunny

A free 20-minute call to set your budget, cities and must-haves.

Get pre-approved

Sunny connects you with lenders who offer the CalHFA and GSFA programs above.

Tour and offer

Homes sell in about 43 to 45 days here. Sunny tells you what will win, and what's overpriced.

Inspections

Your contingency window to inspect, appraise and walk away if needed.

Escrow

Usually 30 to 45 days. Sunny keeps lender, escrow and title moving.

Get your keys

Final walk-through, signing, and the house is yours.

First-time buyer questions

Do I need 20% down?

No. Conventional loans start at 3% down for first-time buyers, FHA at 3.5%, and VA at 0%. Programs like CalHFA MyHome can cover part of that.

Can family help with my down payment?

Yes. Most loans allow gift funds from family with a signed gift letter. It's very common, and Sunny walks families through the paperwork.

Who pays for escrow and title in San Bernardino County?

By local custom, the seller usually pays the owner's title policy and the county transfer tax, and escrow fees are often split. Everything is negotiable, and Sunny will ask for seller credits when the market allows.

What is Mello-Roos?

A special tax in many newer communities that pays for local schools, roads and parks. It's on your property tax bill and can add a few hundred to a few thousand dollars a year, so always check it before you offer.

Can I buy without a long US credit history?

Often, yes. Some lenders use alternative credit (rent, utilities, phone bills) or ITIN loans. Sunny works with buyers new to the US and can connect you with the right lender.

Ready to stop renting?

Sunny is a 2-time eXp ICON Agent and a RealTrends Verified Top 1.5% Realtor. He works in English, Hindi, Punjabi, Bhojpuri and Magahi, with conversational Spanish, and treats every first-time buyer like family.

Call 909-233-0756 Book a free buyer call

Estimates only. This is not a loan offer, a credit check or a guarantee of program eligibility. Typical San Bernardino County costs used: appraisal $650, home inspection $500, lender fees about $1,295 plus origination, buyer's escrow fee about $2 per $1,000 plus $350, lender's title policy about 0.25% of the loan, recording $150, 3 months of tax and insurance reserves and 15 days of prepaid interest. FHA upfront mortgage insurance (1.75%) and the VA funding fee (2.15%) are added to the loan. Market figures: Redfin, Realtor.com and HUD/FHFA 2026 limits, October 2026. Your lender's Loan Estimate shows your actual costs. Sunny Randhir Singh, eXp Realty of California, DRE #02106722. Equal Housing Opportunity.